Business Services
For many SMSF trustees, property is one of the most significant assets held by their SMSF. Unlike personally owned assets, there is a legal requirement that all SMSF assets are valued each 30 June. This can be a simple process for assets that have a ready market like listed shares, however the process for other assets like property can be more onerous. Trustees are responsible for determining the market value of fund assets. After your annual financial statements are prepared your fund auditor will need to see objective and supportable evidence that backs up how you have arrived at the market value. Trustees have the option to use a qualified independent valuer for this and should consider this where an asset represents a significant part of the fund’s value or might be difficult to value. Where trustees choose not to use an independent valuer, they will need to be able to support asset valuations with evidence from multiple sources. Typically, for property this may include: Recent comparable sales – Generally at least 3 and the properties should be genuinely comparable in terms of size and location. A real estate agent appraisal that also includes comparable sales. Net income yields for commercial property (generally not sufficient evidence on its own). The ATO includes some helpful guidance on this in their Guide to valuing SMSF assets. Where an SMSF holds property that meets the business real property (BRP) definition it is possible that this property can be leased to a business that is operated by a member or a related party of the SMSF. However, the fact that an arrangement like this is permitted does not mean the fund trustees can charge a non-market rate of rent. When a rental arrangement is entered into with a related party of the super fund, that arrangement should be on arm’s length (commercial) terms and this should be supported by a rental appraisal. An easy way to think about this is – do all the lease terms reflect an arrangement that would be agreed to if the tenant was an unrelated third party? To evidence that a related party arrangement is on arm’s length (commercial) terms an auditor should be provided with; A properly documented lease; A rent appraisal when the lease was first entered into; Evidence that the arrangement is operating based on the terms of the lease; and Evidence that where a prior lease term has expired the terms have been reset to market value – backed up by a new rent appraisal. Although your financial year 2026 SMSF audit might not be taking place for some months, the process can be much smoother where SMSF trustees are proactive and start to compile this evidence in advance, rather than waiting for the auditor’s request.
At the Federal Budget in May 2026, the Government announced that it would reintroduce a loss carry back tax offset for companies, providing a crucial buffer to any business facing difficult trading conditions.
Why Allied Health Practices Need an Accountant Who Actually Understands Allied Health
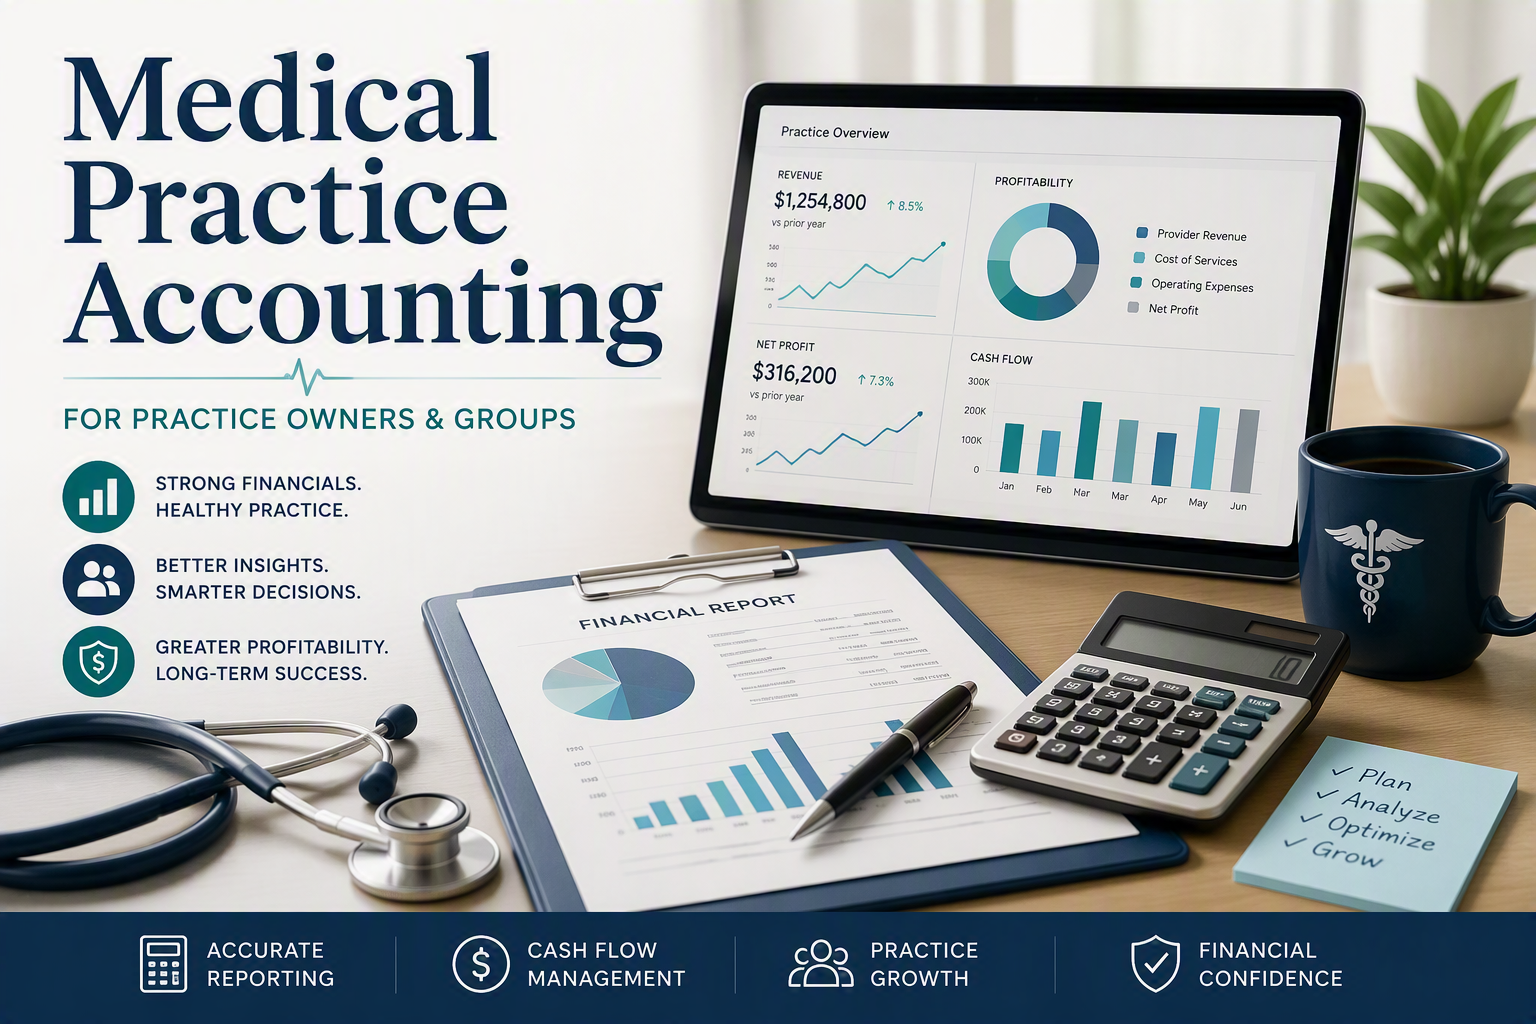
Medical Practice Accounting for Practice Owners & Groups
Running a successful medical practice requires more than delivering excellent patient care. Strong financial management is essential for maintaining profitability, supporting growth, meeting compliance obligations, and ensuring the long-term sustainability of the practice.
Discover practical tax planning strategies for medical specialists in Australia. Learn how proactive structuring, superannuation, practice planning and wealth strategies can help you build long-term financial success.
From 1 July 2026, thousands more businesses—including accounting and professional services firms—are now regulated under Australia’s anti-money laundering and counter-terrorism financing (AML/CTF) laws.
Should Contracting Doctors in Private Practice Use a Discretionary Trust or Operate as Sole Traders?
Structures for Doctors in Private Practice by Clarke McEwan Chartered Accountants - Qld's Medical Tax Experts
Keeping Your Self-Managed Super Fund Compliant
