Is there a problem paying your super when you die?

Clarke McEwan Accountants

The Government has announced its intention to introduce mandatory standards for large superannuation funds to, amongst other things, deliver timely and compassionate handling of death benefits. Do we have a problem with paying out super when a member dies?


The value of superannuation in Australia is now around $4.1 trillion. When you die, your super does not automatically form part of your estate but instead, is paid to your eligible beneficiaries by the fund trustee according to the fund rules, superannuation law, and any death benefit nomination you made.


Complaints to the Australian Financial Complaints Authority (AFCA) about the handling of death benefits surged sevenfold between 2021 and 2023. The critical issue was delays in payments. While most super death benefits are paid within 3 months, for others it can take well over a year. The super laws do not specify a time period only that super needs to be paid to beneficiaries “as soon as practicable” after the death of the member.


How to make sure your super goes to the right place


Death benefits are a complex area. The superannuation fund trustee has discretion over who gets your super benefits unless you have made a valid death nomination. If you don’t make a decision, or let your nomination lapse, then the fund has the discretion to pay your super to any of your dependents or your estate.


There are four types of death nominations:


1. Binding death benefit nomination Directs your super to your nominated eligible beneficiary, the trustee is bound by law to pay your super to that person as soon as practicable after your death. Generally, death benefit nominations lapse after 3 years unless it is a non-lapsing binding death nomination.


2. Non-lapsing binding death benefit nomination If permitted by your trust deed, a non-lapsing binding death benefit nomination will remain in place unless you cancel or replace it. When you die, your super is directed to the person you nominate.


3. Non-binding death nomination A guide for trustees as to who should receive your super when you die but the trustee retains control over who the benefits are paid to. This might be the person you nominate but the trustees can use their discretion to pay your super to someone else or to your estate.


4. Reversionary beneficiary If you are taking an income stream from your superannuation at the time of your death (pension), the payments can revert to your nominated beneficiary at the time of your death and the pension will be automatically paid to that person. Only certain dependents can receive reversionary pensions, generally a spouse or child under 18 years.


Who is eligible to receive your super?


Your super can be paid to a dependent, your legal representative (for example, the executor of your will), or someone who has an interdependency relationship with you. A dependent for superannuation purposes is “the spouse of the person, any child of the person and any person with whom the person has an interdependency relationship”. An interdependency relationship is where someone depends on you for financial support or care.


What happens if I don’t make a nomination?


If you have not made a death benefit nomination, the trustees will decide who to pay your superannuation to according to state or territory laws. This will be a superannuation dependent or the legal representative of your estate to then be distributed according to your Will.


Where it can go wrong


There have been a number of court cases over the years that have successfully contested the validity of death nominations. For a death nomination to be valid it must be in writing, signed and dated by you, and witnessed. The wording of your nomination also needs to be clear and legally binding. If you nominate a person, ensure you use their legal name. If your super is to be directed to your estate, ensure the wording uses the correct legal terminology.


One of the reasons for delays in paying death benefit nominations cited by the funds is where there is no nomination (or it is expired or invalid), there are multiple potential claimants, and the trustee needs to work through sometimes complex family scenarios.


The bottom line is, young or old, check your nominations with your superannuation fund and make sure you have the right type of nomination in place, and it is valid and correct. While there still might be a delay in getting your super where it needs to go if you die, the process will be a lot quicker and less onerous for your loved ones.
By Clarke McEwan • October 21, 2026
Superannuation law requires trustees of SMSFs to formulate, regularly review and give effect to an investment strategy that has regard to the whole of the circumstances of the fund. Although there is nothing in the law stating a timeframe that may define ‘review regularly’, it is commonly accepted that this would be at least annually. This aligns with comments on the ATO’s website where they expect reviews to occur at least annually. Some trustees will undertake an annual review leading up to, or at the beginning of a new financial year, while others will undertake the review as part of reviewing the completed financial accounts from the previous financial year. Neither is the right or wrong option, and you must consider what is best for your situation. Either way, you will need to be able to show your fund’s auditor that you have reviewed the investment strategy and documented any decisions made, whether it be recording changes deemed necessary or determined the existing strategy remains appropriate. There may be other times that it is appropriate to review the investment strategy. These may include when: There is a market correction; A member joins or leaves the fund; A member starts a pension in the fund. An investment policy will generally be comprised of two parts: 1. Investment objective – this part outlines the fund’s objectives and expected outcomes. For example, an objective may be to achieve a certain level of return over a certain period. This would generally take into account the age of the members, their retirement needs and investment risk profile. 2. Investment strategy – this part outlines how the fund will achieve the stated objectives. For example, it may include investment asset ranges or specific assets that will be held. When reviewing your fund’s investment strategy, consideration must be given to: The risk of holding particular investments and their returns, with regards to the fund’s objectives and expected cashflow requirements; Composition of investments and the risk of inadequate diversification; Liquidity of investments, with regards to expected cashflow requirements; Ability to discharge existing and prospective liabilities; and Whether insurance cover for one or more members should be held by the fund. Although these points need to be considered, it is up to the trustees to determine how they are applied, based on the circumstances of the fund. As an example, you must consider the diversification of the fund’s assets, but that does not mean you are required to have a diversified investment strategy. Many funds hold just a property and a bank account, and this may be appropriate for those funds. However, the trustees should document what consideration they gave to diversification, why the lack of diversification is appropriate and why they have chosen these particular assets. Likewise, there is no legal requirement to hold insurance cover for the members, but you do need to document that it has been considered. As noted above, a member starting a pension may be reason to review the fund’s investment strategy. This is due to the fact that this is likely to change the liquidity considerations and investment profile of the fund. When members are all in the pre-retirement growth phase, expenses are usually more predictable and there isn’t a need for many funds to hold large cash reserves. Once members reach the point they are accessing their benefits, as either pension or lump sum payments (or both), cashflow, liquidity and a potential cash buffer become a more important consideration. It is not uncommon that leading up to the end of any given financial year we will field enquiries and concerns from trustees that do not have the cash to satisfy even the minimum pension requirements for the year. While there may be several reasons for this, it should raise questions about the appropriateness of the fund’s current investment strategy and considerations as to whether a review of the asset holdings is warranted. If we revisit the one property and one bank account funds mentioned early, this may have been a reasonable strategy during the growth phase, but does it remain so during the drawdown phase? Although many people are comfortable with property and Australian investors in general have an affinity for the old bricks and mortar, this does not mean it is an appropriate investment in all circumstances. If the rental income from the property cannot support your retirement needs and minimum pension withdrawal requirements, something needs to change. This will hold true for any other investment that may not be easily sold, such as holdings in unlisted companies and trusts. Reviewing your fund’s investment strategy and giving consideration to the needs of the members and the asset holdings of the fund should not be seen as just a tick-a-box legal requirement. You’ve worked hard to build you retirement wealth and when the time comes, you want to be able to enjoy it. Having an appropriate investment strategy that will allow this is an important element of running an SMSF. Have you reviewed your strategy lately?
By Clarke McEwan • October 21, 2026
Federal Parliament has closed an unintended loophole in the recent negative gearing and capital gains tax reforms that became widely known as the “widow tax”. At the same time, the Government also fixed a technical issue that could have affected people who first use a main residence to generate rental income after Budget night on 12 May 2026. What the problem was As you might be aware, the tax rules have recently been changed to ensure that losses generated from residential rental properties from 1 July 2027 can be ‘quarantined’. This means that they can only be offset against income or capital gains generated from other residential rental properties. However, the changes won’t generally apply to properties that were purchased by the relevant taxpayer before 12 May 2026. However, a problem could arise when an ownership interest in a property passes to someone as a result of the death of the original owner or because of a relationship breakdown and this occurs after 12 May 2026. Under the original version of the new rules, that transfer could be treated as a new acquisition. This could have meant that a surviving spouse or former partner risked losing the protected negative gearing treatment that had applied to the property in the hands of the previous owner. How it was fixed The Government moved quickly once the issue was identified. Some new rules now specifically protect people who acquire a residential property interest from a spouse because of death or relationship breakdown. The rules can also potentially protect someone who inherits an additional ownership interest in a rental property from a co-owner who isn’t their spouse. Case study 1 – the widow tax fix Sarah and David bought a rental unit in 2019 as equal joint owners. The property has always been negatively geared, with annual rental losses of around $8,000 offset against their other income each year. Under the original May 2026 reforms, the property was protected because it was acquired well before Budget night. However, if David had died and the property transferred fully into Sarah’s name, the additional 50% interest that Sarah inherited from David’s estate risked being treated as a new acquisition. Sarah could have lost the ability to claim the losses generated from this interest in the property against her other income. With the updated rules now in place, that outcome is avoided. Because the transfer occurs due to the death of a spouse, Sarah keeps the original protected treatment and can continue offsetting the rental losses in the same way as before. Former main residences A related technical issue also needed fixing. Under the original rules there was a risk that an existing main residence purchased before 12 May 2026 could lose its protected status if it was later first used to generate taxable rental income after that date. This was because of the interaction with a long-standing tax rule that can treat someone as if they had reacquired a former main residence when it is first used to produce income. The Government has now passed legislation to correct this. The new rules specifically disregard that “first use to produce income” rule when determining the acquisition date for negative gearing purposes. Case study 2 – renting out a former home James bought his home in 2018 and has lived in it as his main residence ever since. In 2027 he decides to move in with his partner and rent the property out for the first time. Under the original drafting of the 2026 reforms, first renting the property after 12 May 2026 risked resetting its acquisition date. That could have caused the property to be treated as a post-Budget night acquisition and subjected to the tighter negative gearing limits. With the new rules now in place, that reset is disregarded for negative gearing purposes. Because James originally acquired the property before 7:30 pm on 12 May 2026, it keeps its original acquisition date. He can continue to offset any rental losses in the same way as if the property had always been an investment property acquired before Budget night. Why these fixes matter Both changes remove sources of unexpected cash-flow disruption. The “widow tax” fix protects people at a difficult personal time. The main residence clarification gives homeowners greater flexibility if their circumstances change and they later decide to rent out a property they already own. What you should do now If you own a jointly held investment property acquired before 12 May 2026, the “widow tax” fix provides reassurance that a future transfer on death or separation should not remove negative gearing rights, but the rules are still complex and it is always best to have the position checked. If you own a main residence bought before 12 May 2026 and are considering renting it out in future, the new rule means the property should keep its original acquisition date for negative gearing purposes, but there could still be some complex CGT implications. Keep clear records of the original purchase date and ownership history. If either situation applies to you and you would like confirmation of how the amended rules work in your circumstances, contact us.
By Clarke McEwan • October 21, 2026
More than $21 billion in lost and unclaimed superannuation is currently sitting idle across Australia, according to the latest ATO figures. The average lost account holds around $41,000. Last year alone the ATO reunited more than $1.1 billion with members. That is real money that could be working harder for your retirement. Tax time is the natural moment to check whether any of it belongs to you. How super becomes “lost” Super generally becomes lost when an account becomes inactive and the fund can no longer contact the member. Common triggers include: Changing jobs and leaving an old account behind Moving house or updating your phone number without telling the fund Changing your name When the fund cannot reach you, the account may be classified as lost. In some cases, the balance is eventually transferred to the ATO to hold until the rightful owner claims it. The money does not disappear; it simply sits waiting to be reunited with its owner. A five-minute health check Finding lost super is straightforward and free. The quickest way is through ATO online services via myGov: 1. Log in to myGov and open the ATO section. 2. Select Super, then Fund details. 3. You will see any active accounts plus any lost or ATO-held super linked to your tax file number. You can also use the ATO app or call the automated lost super search line on 13 28 65. A paper form is available if you prefer. Many people are surprised by what turns up from old accounts from early jobs, small balances that have grown over time, or larger amounts they had completely forgotten about.  Especially valuable if you are approaching retirement For clients still decades from retirement, finding lost super is useful. For those at or approaching retirement age it can be particularly meaningful. An extra $20,000 or $40,000 (or more) can make a noticeable difference to the size of the nest egg available to draw on. Even smaller amounts compound further once consolidated into a single active account that continues to earn returns and attract any future contributions. One important practical warning before you consolidate If you decide to roll multiple accounts into one preferred fund, check the insurance cover attached to each account first. Death, total and permanent disability, or income-protection cover that comes with a super account can sometimes end when the balance is rolled over. Losing that cover without realising it can leave a gap in your protection at the exact time you may need it most. Speak with your fund or adviser before consolidating so you understand exactly what will transfer and what will not. The commercial upside is simple Every dollar sitting in a lost or low-balance account is potentially earning less than it could, or incurring unnecessary fees. Bringing the money into one active account usually reduces fees, improves investment choice, and makes it easier to keep track of your overall position. The ATO’s reunification figures show that when people do the search, meaningful amounts are regularly returned. The process takes only a few minutes and costs nothing. Given that more than $21 billion is currently waiting to be claimed, the odds that some of it belongs to you are higher than many people expect. You can start the free search here: https://www.ato.gov.au/forms-and-instructions/superannuation-searching-for-lost-superannuation If you would like help interpreting what you find, or advice on whether consolidation makes sense in your circumstances (including the insurance check), just get in touch. A short conversation now can put money back into your retirement savings that might otherwise stay forgotten.
By Clarke McEwan • October 21, 2026
Travel records under the ATO microscope
By Clarke McEwan • October 7, 2026
Owning your business premises can build long-term wealth and eliminate rent increases. Leasing can offer greater flexibility and preserve cash flow. Every business is different. Let us help you analyse the costs and benefits so you can make the right decision. 📞 Get in touch today.
By Clarke McEwan • September 18, 2026
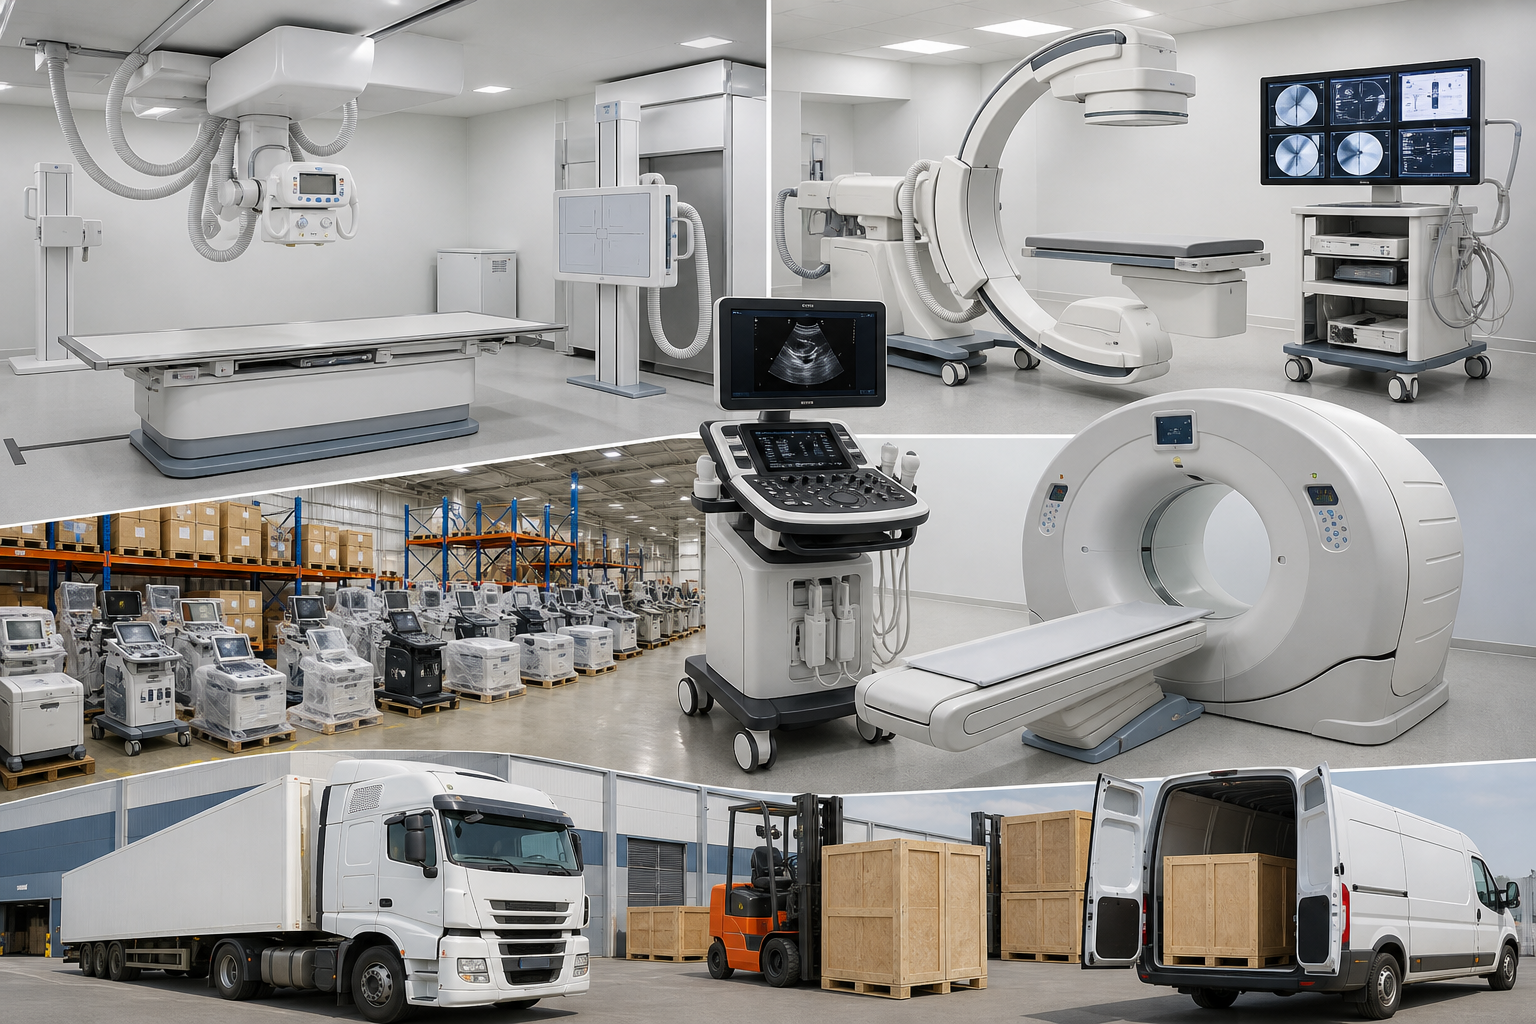
There are certain items of equipment, machinery and hardware that are essential to the operation of your business – whether it’s the delivery van you use to run your client deliveries, diagnostic equipment in your medical practice or the high-end digital printer to run your print business. But when a critical business asset is required, should you buy this item outright, or should you lease the item and pay for it in handy monthly instalments? To buy or to lease? That is the question Buying new pieces of business equipment, plant, machinery or vehicles can be an expensive investment. So, depending on your financial situation, it’s important to weigh up the pros and cons of buying, or opting for a leasing option. First of all, let’s look at why you might decide to buy the item… Buying: the pros and cons: - Pro: It’s a tangible asset – when you buy an item, you own the item outright and it will appear on your balance sheet as one your business assets. As such, by owning these assets outright you increase the perceived capital and value of your business. You can also claim the cost of the asset against your capital allowance for tax purposes. - Pro: It’s yours for the life of the asset – once you own the item, you have full use of the equipment for the duration of the life of the asset. Your use of the asset isn’t reliant on you being able to keep up regular lease payments, and if your financial circumstances change then you can sell the asset to free up the capital. - Con: It’s an expensive outlay – paying for the item up-front is a large outlay for the business and will require you having the cash to cover this cost. Spending a large lump sum in this way may take cash away from other areas of the business, so you need to be 100% sure that this purchase is the right decision and a sound investment. - Con: You may require extra funding – if you don’t have the liquid cash available to buy the item outright, you may need to take out a loan. Asset finance is available from funding providers, but does tie you into a loan agreement that will add to your liabilities as a business – reducing your worth on the balance sheet. Leasing: the pros and cons: - Pro: Leasing has a cheaper entry point – if the item you need to purchase has a large price tag, leasing allows you to make use of the asset without the cost of buying it in full. For start-ups and smaller businesses with minimal capital behind them, this can make leasing a very attractive option. You may not own the asset, but you can make use of it – and this may be the difference between the success or failure of your business. - Pro: You can spread the cost – there is still an associated cost of leasing, but you can spread the cost over a longer period, making it easier to find the necessary liquid cash to meet your lease payments. With this money saved, you can then invest in other areas of the business, helping you to expand, grow and bring in more customers and revenue. - Con: You don’t own the asset – there are different types of leasing agreement. Under a capital lease, you do own the asset (once you’ve paid if off). But if you opt for an operating lease, this is a more short-term lease and you won’t own the asset at the end of the contract. Ownership does have its advantages (including being able to sell off the asset if required) so it’s important to consider what kind of leasing agreement you’re entering into and what the advantages/disadvantages may be. - Con: You may pay more in the long run – most leasing agreements will attract additional costs and interest on your agreement, so you may well end up paying more than the market price for your asset in the long term. If you can cope with the higher cost, this is fine, but bear in mind that buying outright may have offered greater value. - Con: You may lose the use of the asset – if you can’t keep up your lease payments (due to poor cashflow for example) then the owner of the lease agreement may recall the asset. If this item is crucial to your business model, losing this key asset can have a profound impact on your ability to operate. In this respect, leasing is a more risky prospect, but also an easier option for businesses with less cash to splash.Talk to us about whether buying or leasing is the best way forward. Whether you opt to buy or lease your equipment isn’t always a straightforward decision to make – so it’s a good idea to consult with your accountant early on in the decision-making process. We’ll help you review your current financial position, assess your available cashflow and look at your regular cost base to decide whether buying or leasing is the right thing for your business.
More Posts