27 Social media tools for business

Clarke McEwan Accountants

Social media isn't just about viral videos or selfies. For consumers, sites and apps such as Facebook, Instagram, and Twitter are playing an increasingly large role in their path to purchase.

This is why it's so important for retailers to invest in social media marketing. Having a strong presence in relevant social networks not only gives you an avenue to communicate with your audience, it also allows you to stay in the radars of your customers. This in turn, increases the likelihood of a shopper choosing your brand when they're ready to buy.

To that end, we've compiled a list of tools you can use to streamline your social media efforts. From social network management apps that'll save you time, to social commerce solutions that'll enable you to sell products to your fans and followers, the following tools are essential for any retailer who wants to win at social.

Facebook

Call to Action buttons - Businesses can add call-to-action buttons on their Pages and ads. Admins can select from seven calls to action, including Book Now, Contact Us, Use App, Play Game, Shop Now, Sign Up, and Watch Video.

Check out this example from Tory Burch, which has a "Shop Now" button on its page.

To add a call-to-action button on your Page, click the "Create Call-to-Action" button found at the top part of your page, on your cover photo.

Facebook Bluetooth Beacons - Beacons have been a hot topic in the retail industry for some time, and it looks like Facebook now has its own Beacon initiative. The company launched Facebook Bluetooth beacons, which are devices that retailers can use to help customers learn more about the business whenever they visit the store. Retailers will be able to deliver certain information or messages to customers such as a welcome note or a prompt to "like" the business' page.

All you need to do is install the beacons in your store, and they will then connect with smartphone users who have Facebook location services turned on.

Facebook Bluetooth beacons can be requested for free here .

Woobox Custom Tab - Woobox lets you install customized tabs to your Facebook page. It lets you add forms, embed external sites, fangate content, and it even create your own tab designs.

LikeAlyzer - Need a quick analysis of your Facebook Page? Just enter your URL into LikeAlyzer's search field and it will generate a report that contains your page score, along with information on what you're doing right and what can be improved. It even offers recommendations to help boost Page performance.

Facebook word blocker and profanity filter - These tools make moderating comments a bit easier. The word blocker allows you to create filters that automatically hide comments or posts that contain words or phrases that you specify.

The profanity filter on the other hand, lets you restrict (or enable) certain levels of profanity for your page. According to the social network, "Facebook determines what to block by using the most commonly reported words and phrases marked offensive by the community."

You can find both these tools by clicking the Settings button at the top of your Page.

Twitter

Followerwonk - One of the most popular Twitter analytics solutions in the social realm, Followerwonk lets you "find, analyze, and optimize" for social growth. It offers features such as follower analysis, bio searches, follower tracking, and more.

Twitter Profile Analysis by Klear - This is a free tool that gives you a snapshot of how your (or anyone else's) Twitter profile is doing. It measures activity level, popularity, and responsiveness, and it also identifies top content.

Topsy - Want to see who's tweeting about your brand or any other topic? Just enter the term or phrase into Topsy's search field and it'll generate a list of Twitter users talking about the term or topic you searched for. You can even enter full URLs to see who's shared your content. Perfect if you want to check out the people tweeting out your content.

Tweepi - Tweepi is a great tool for managing friends and followers on Twitter. It lets you view and sort the users you're following, as well as those who aren't following you back.

Twitterfall - If you need to monitor Twitter trends in real-time, look no further. Twitterfall displays tweet searches as they happen. This is great if you're monitoring trends or events as they're happening. Many social media experts, including Kelly Mahoney, social media manager for CompTIA , use this tool when running or participating in Twitter chats.

"It's great because it allows you to visually display tweets in real-time. You can also retweet, reply, favorite, and follow people directly from the platform if you sign in to it through Twitter's API."

Instagram

Crowdfire - Crowdfire enables you to easily manage your Instagram follower and following lists. It lets you view your non-followers and offers features to help you clean up your account. It also has a "CopyFollowers" feature that lets you quickly view another account's followers. Perfect if you're looking to follow relevant accounts.

TakeOff - Another app by Crowdfire, TakeOff allows you to schedule your Instagram posts at the most optimal times. It calculates the best time to post based on when your audience is most likely to be online, increasing your chances of getting in front of your followers. It also has additional features, including smart tags, photo search, and multiple account support.

Iconosquare - Analyze your Instagram account and get cool stats with Iconosquare. This tool gives you an overview of the number of likes and comments you received, and it also scores your account's engagement levels.

Repost - As its name clearly implies, this app lets you repost photos and videos from your Instagram feed and likes. It also lets you bookmark posts so you could repost them at a later time.

Snapwidget - Show off your Instagram feed on your website with Snapwidget. Used by over 100,000 websites, this solution lets you create and customize a grid, slideshow, or photo map of your Instagram posts quickly and easily.

Pinterest

Pinterest Analytics - Pinterest Analytics helps you better understand your users and content. It shows you data on your Pinterest profile, your audience, and your website, allowing you to get insights into how users are engaging with your content both on your website and Pinterest profile.

Note: You'll need a business Pinterest account to access analytics. You can either create one, or convert your existing profile on business.pinterest.com .

Tailwind - Tailwind provides an array of features to help you stay on top of your Pinterest efforts. With it you can schedule Pins, analyze trends, measure results, and monitor Pinterest activities, among others.

PinAlerts - Think of PinAlerts as Google Alerts, but for Pinterest. It sends you an email alert whenever someone Pins an image from your website, thus giving insights into which of your images are popular on Pinterest. It also lets you see who's Pinning your images so you can reach out to them.

Social commerce tools

If you're looking to make your social accounts more shoppable so you can sell directly to your fans and followers, the following tools are worth looking into:

Like2Buy - As we mentioned in our 2015 Retail Trends piece , Like2Buy is one of the leading solutions for making Instagram more shoppable. Here's how it works: A customer who'd like to purchase an item they see on your feed can tap on the Like2Buy link found on Instagram profile. Clicking the link will take them to the your Like2Buy site, which looks similar to your Instagram page. When the shopper taps on an image, they'll be taken directly to its product page, where they can find more details and proceed to checkout.

Tapshop - Tapshop works by giving you a branded link that you can display on your Instagram profile. When users click through that link, they'll be taken to "a custom page of products they've liked, and get an email with links directly to your product pages."

Soldsie and Spreesy - These are comment-based selling solutions that enable retailers sell through Instagram and Facebook comments. When shoppers see an image of an item they'd like to buy, they would simply need to leave a comment indicating their purchase intent, and these services will automatically generate an invoice or checkout link, then send it via email.

Note: Soldsie also has a solution called Have2Have.It, which, similar to Tapshop and Like2Buy, lets retailers set up a curated page that has the same look and feel as their brand's Instagram feed. From there, users can learn more about their products and head straight to the retailer's ecommerce site if they want to make a purchase

General social media management and monitoring

Hootsuite - Hootsuite is one of the most a powerful and extensive social media management solution out there. It allows you to manage your Twitter, Facebook, Google+, LinkedIn, Instagram, and even WordPress account from one dashboard. You can view and schedule posts right from Hootsuite, saving you time and energy.

Buffer - If you're looking for a more lightweight tool with a simple interface, then Buffer is worth checking out. It's an excellent social media scheduling tool that works with Twitter, Facebook, LinkedIn, Google+, and Pinterest. Adding posts to your queue can be done with one click, and Buffer can automatically create a scheduling plan for you, or you can set pre-determined times for when posts should go out.

Handy design tools for creating shareable images

PicMonkey - Want to create beautiful images but don't have the design skills to do so? Check out PicMonkey, a web-based solution that makes it easy for you to edit, touch-up, and design images for your blog posts and social media updates. It even has a collage maker for those who can't decide on just one picture to post.

Canva - Canva is a powerful-but super user friendly-graphic tool for people who are "design-challenged." Like most graphic design solutions, Canva lets you easily re-touch and edit images. On top of that, it also offers preset templates for Facebook posts, cover images, posters, flyers, and blog posts, making it easy for you to get started on projects. What's more, Canva has a library of fonts, graphics, and photos that you can add to your design with a quick drag-and-drop feature.

Share As Image - If you like putting text on top of images, Share As Image offers an extremely simple solution. It's works as a Chrome extension and bookmarklet that you can access from any website. All you have to do is highlight text on the page, click the bookmarklet, and Share As Image will turn it into an image ready to be shared across social media.

Your turn

Did we miss anything? Are you using any awesome social media tools that aren't on this list? Tell us about them in the comments.

About Francesca Nicasio

Francesca Nicasio is Vend's Retail Expert and Content Strategist. She writes about trends, tips, and other cool things that enable retailers to increase sales, serve customers better, and be more awesome overall. She's also the author of Retail Survival of the Fittest, a free eBook to help retailers future-proof their stores. Connect with her on LinkedIn, Twitter, or Google+.
By Clarke McEwan • October 21, 2026
Superannuation law requires trustees of SMSFs to formulate, regularly review and give effect to an investment strategy that has regard to the whole of the circumstances of the fund. Although there is nothing in the law stating a timeframe that may define ‘review regularly’, it is commonly accepted that this would be at least annually. This aligns with comments on the ATO’s website where they expect reviews to occur at least annually. Some trustees will undertake an annual review leading up to, or at the beginning of a new financial year, while others will undertake the review as part of reviewing the completed financial accounts from the previous financial year. Neither is the right or wrong option, and you must consider what is best for your situation. Either way, you will need to be able to show your fund’s auditor that you have reviewed the investment strategy and documented any decisions made, whether it be recording changes deemed necessary or determined the existing strategy remains appropriate. There may be other times that it is appropriate to review the investment strategy. These may include when: There is a market correction; A member joins or leaves the fund; A member starts a pension in the fund. An investment policy will generally be comprised of two parts: 1. Investment objective – this part outlines the fund’s objectives and expected outcomes. For example, an objective may be to achieve a certain level of return over a certain period. This would generally take into account the age of the members, their retirement needs and investment risk profile. 2. Investment strategy – this part outlines how the fund will achieve the stated objectives. For example, it may include investment asset ranges or specific assets that will be held. When reviewing your fund’s investment strategy, consideration must be given to: The risk of holding particular investments and their returns, with regards to the fund’s objectives and expected cashflow requirements; Composition of investments and the risk of inadequate diversification; Liquidity of investments, with regards to expected cashflow requirements; Ability to discharge existing and prospective liabilities; and Whether insurance cover for one or more members should be held by the fund. Although these points need to be considered, it is up to the trustees to determine how they are applied, based on the circumstances of the fund. As an example, you must consider the diversification of the fund’s assets, but that does not mean you are required to have a diversified investment strategy. Many funds hold just a property and a bank account, and this may be appropriate for those funds. However, the trustees should document what consideration they gave to diversification, why the lack of diversification is appropriate and why they have chosen these particular assets. Likewise, there is no legal requirement to hold insurance cover for the members, but you do need to document that it has been considered. As noted above, a member starting a pension may be reason to review the fund’s investment strategy. This is due to the fact that this is likely to change the liquidity considerations and investment profile of the fund. When members are all in the pre-retirement growth phase, expenses are usually more predictable and there isn’t a need for many funds to hold large cash reserves. Once members reach the point they are accessing their benefits, as either pension or lump sum payments (or both), cashflow, liquidity and a potential cash buffer become a more important consideration. It is not uncommon that leading up to the end of any given financial year we will field enquiries and concerns from trustees that do not have the cash to satisfy even the minimum pension requirements for the year. While there may be several reasons for this, it should raise questions about the appropriateness of the fund’s current investment strategy and considerations as to whether a review of the asset holdings is warranted. If we revisit the one property and one bank account funds mentioned early, this may have been a reasonable strategy during the growth phase, but does it remain so during the drawdown phase? Although many people are comfortable with property and Australian investors in general have an affinity for the old bricks and mortar, this does not mean it is an appropriate investment in all circumstances. If the rental income from the property cannot support your retirement needs and minimum pension withdrawal requirements, something needs to change. This will hold true for any other investment that may not be easily sold, such as holdings in unlisted companies and trusts. Reviewing your fund’s investment strategy and giving consideration to the needs of the members and the asset holdings of the fund should not be seen as just a tick-a-box legal requirement. You’ve worked hard to build you retirement wealth and when the time comes, you want to be able to enjoy it. Having an appropriate investment strategy that will allow this is an important element of running an SMSF. Have you reviewed your strategy lately?
By Clarke McEwan • October 21, 2026
Federal Parliament has closed an unintended loophole in the recent negative gearing and capital gains tax reforms that became widely known as the “widow tax”. At the same time, the Government also fixed a technical issue that could have affected people who first use a main residence to generate rental income after Budget night on 12 May 2026. What the problem was As you might be aware, the tax rules have recently been changed to ensure that losses generated from residential rental properties from 1 July 2027 can be ‘quarantined’. This means that they can only be offset against income or capital gains generated from other residential rental properties. However, the changes won’t generally apply to properties that were purchased by the relevant taxpayer before 12 May 2026. However, a problem could arise when an ownership interest in a property passes to someone as a result of the death of the original owner or because of a relationship breakdown and this occurs after 12 May 2026. Under the original version of the new rules, that transfer could be treated as a new acquisition. This could have meant that a surviving spouse or former partner risked losing the protected negative gearing treatment that had applied to the property in the hands of the previous owner. How it was fixed The Government moved quickly once the issue was identified. Some new rules now specifically protect people who acquire a residential property interest from a spouse because of death or relationship breakdown. The rules can also potentially protect someone who inherits an additional ownership interest in a rental property from a co-owner who isn’t their spouse. Case study 1 – the widow tax fix Sarah and David bought a rental unit in 2019 as equal joint owners. The property has always been negatively geared, with annual rental losses of around $8,000 offset against their other income each year. Under the original May 2026 reforms, the property was protected because it was acquired well before Budget night. However, if David had died and the property transferred fully into Sarah’s name, the additional 50% interest that Sarah inherited from David’s estate risked being treated as a new acquisition. Sarah could have lost the ability to claim the losses generated from this interest in the property against her other income. With the updated rules now in place, that outcome is avoided. Because the transfer occurs due to the death of a spouse, Sarah keeps the original protected treatment and can continue offsetting the rental losses in the same way as before. Former main residences A related technical issue also needed fixing. Under the original rules there was a risk that an existing main residence purchased before 12 May 2026 could lose its protected status if it was later first used to generate taxable rental income after that date. This was because of the interaction with a long-standing tax rule that can treat someone as if they had reacquired a former main residence when it is first used to produce income. The Government has now passed legislation to correct this. The new rules specifically disregard that “first use to produce income” rule when determining the acquisition date for negative gearing purposes. Case study 2 – renting out a former home James bought his home in 2018 and has lived in it as his main residence ever since. In 2027 he decides to move in with his partner and rent the property out for the first time. Under the original drafting of the 2026 reforms, first renting the property after 12 May 2026 risked resetting its acquisition date. That could have caused the property to be treated as a post-Budget night acquisition and subjected to the tighter negative gearing limits. With the new rules now in place, that reset is disregarded for negative gearing purposes. Because James originally acquired the property before 7:30 pm on 12 May 2026, it keeps its original acquisition date. He can continue to offset any rental losses in the same way as if the property had always been an investment property acquired before Budget night. Why these fixes matter Both changes remove sources of unexpected cash-flow disruption. The “widow tax” fix protects people at a difficult personal time. The main residence clarification gives homeowners greater flexibility if their circumstances change and they later decide to rent out a property they already own. What you should do now If you own a jointly held investment property acquired before 12 May 2026, the “widow tax” fix provides reassurance that a future transfer on death or separation should not remove negative gearing rights, but the rules are still complex and it is always best to have the position checked. If you own a main residence bought before 12 May 2026 and are considering renting it out in future, the new rule means the property should keep its original acquisition date for negative gearing purposes, but there could still be some complex CGT implications. Keep clear records of the original purchase date and ownership history. If either situation applies to you and you would like confirmation of how the amended rules work in your circumstances, contact us.
By Clarke McEwan • October 21, 2026
More than $21 billion in lost and unclaimed superannuation is currently sitting idle across Australia, according to the latest ATO figures. The average lost account holds around $41,000. Last year alone the ATO reunited more than $1.1 billion with members. That is real money that could be working harder for your retirement. Tax time is the natural moment to check whether any of it belongs to you. How super becomes “lost” Super generally becomes lost when an account becomes inactive and the fund can no longer contact the member. Common triggers include: Changing jobs and leaving an old account behind Moving house or updating your phone number without telling the fund Changing your name When the fund cannot reach you, the account may be classified as lost. In some cases, the balance is eventually transferred to the ATO to hold until the rightful owner claims it. The money does not disappear; it simply sits waiting to be reunited with its owner. A five-minute health check Finding lost super is straightforward and free. The quickest way is through ATO online services via myGov: 1. Log in to myGov and open the ATO section. 2. Select Super, then Fund details. 3. You will see any active accounts plus any lost or ATO-held super linked to your tax file number. You can also use the ATO app or call the automated lost super search line on 13 28 65. A paper form is available if you prefer. Many people are surprised by what turns up from old accounts from early jobs, small balances that have grown over time, or larger amounts they had completely forgotten about.  Especially valuable if you are approaching retirement For clients still decades from retirement, finding lost super is useful. For those at or approaching retirement age it can be particularly meaningful. An extra $20,000 or $40,000 (or more) can make a noticeable difference to the size of the nest egg available to draw on. Even smaller amounts compound further once consolidated into a single active account that continues to earn returns and attract any future contributions. One important practical warning before you consolidate If you decide to roll multiple accounts into one preferred fund, check the insurance cover attached to each account first. Death, total and permanent disability, or income-protection cover that comes with a super account can sometimes end when the balance is rolled over. Losing that cover without realising it can leave a gap in your protection at the exact time you may need it most. Speak with your fund or adviser before consolidating so you understand exactly what will transfer and what will not. The commercial upside is simple Every dollar sitting in a lost or low-balance account is potentially earning less than it could, or incurring unnecessary fees. Bringing the money into one active account usually reduces fees, improves investment choice, and makes it easier to keep track of your overall position. The ATO’s reunification figures show that when people do the search, meaningful amounts are regularly returned. The process takes only a few minutes and costs nothing. Given that more than $21 billion is currently waiting to be claimed, the odds that some of it belongs to you are higher than many people expect. You can start the free search here: https://www.ato.gov.au/forms-and-instructions/superannuation-searching-for-lost-superannuation If you would like help interpreting what you find, or advice on whether consolidation makes sense in your circumstances (including the insurance check), just get in touch. A short conversation now can put money back into your retirement savings that might otherwise stay forgotten.
By Clarke McEwan • October 21, 2026
Travel records under the ATO microscope
By Clarke McEwan • October 7, 2026
Owning your business premises can build long-term wealth and eliminate rent increases. Leasing can offer greater flexibility and preserve cash flow. Every business is different. Let us help you analyse the costs and benefits so you can make the right decision. 📞 Get in touch today.
By Clarke McEwan • September 18, 2026
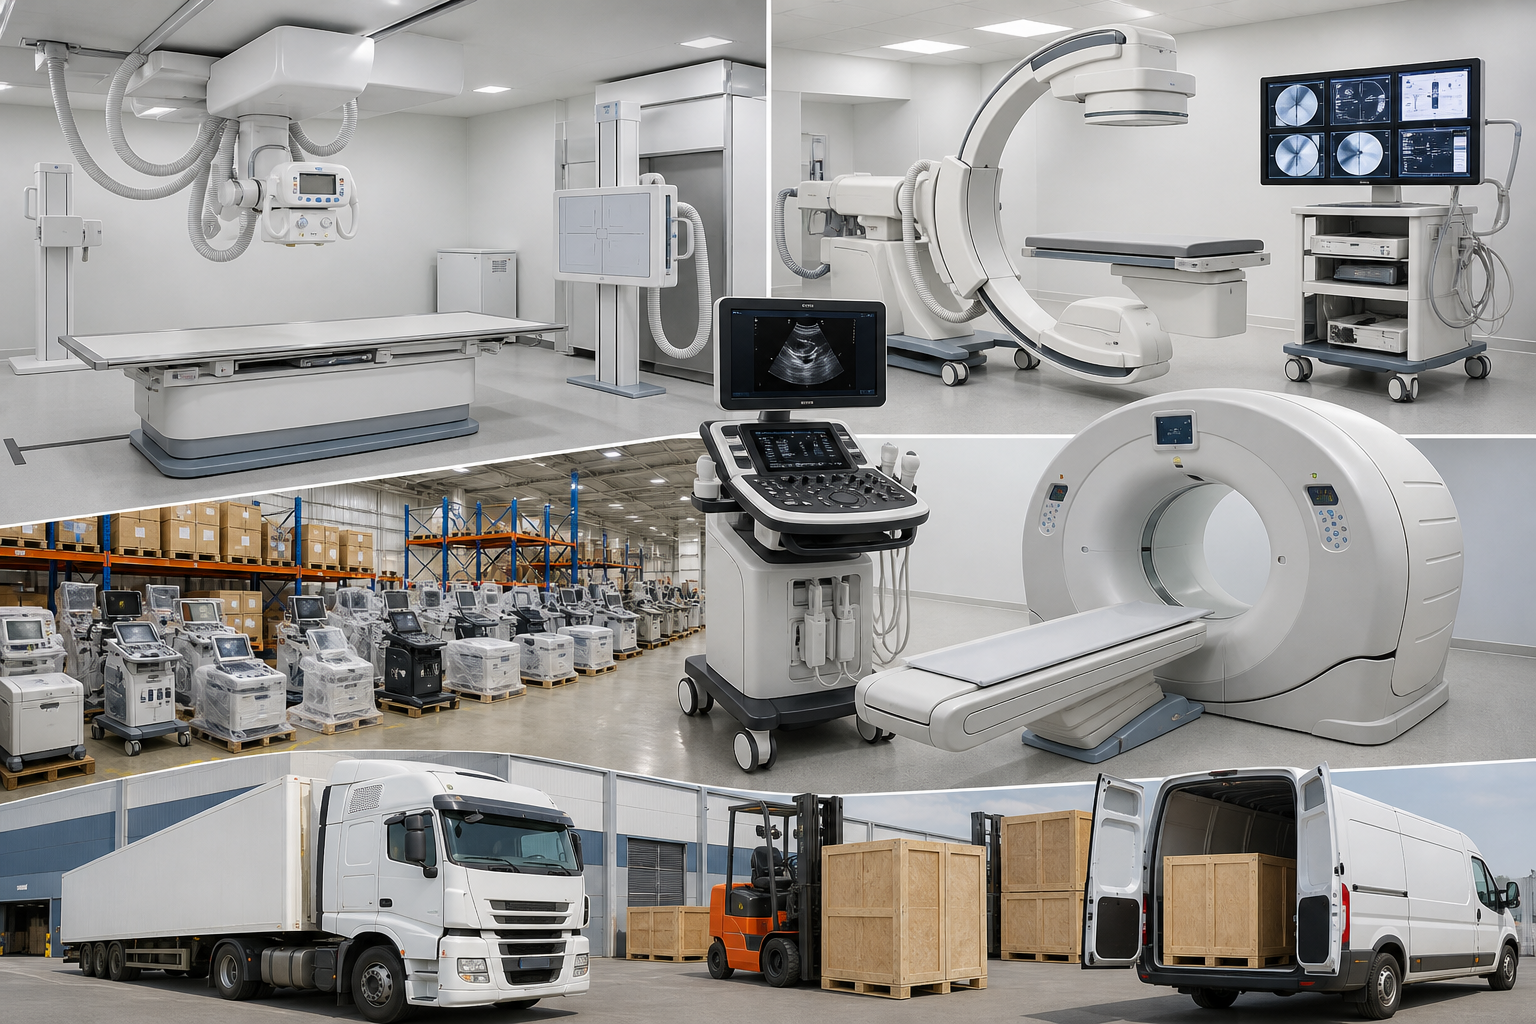
There are certain items of equipment, machinery and hardware that are essential to the operation of your business – whether it’s the delivery van you use to run your client deliveries, diagnostic equipment in your medical practice or the high-end digital printer to run your print business. But when a critical business asset is required, should you buy this item outright, or should you lease the item and pay for it in handy monthly instalments? To buy or to lease? That is the question Buying new pieces of business equipment, plant, machinery or vehicles can be an expensive investment. So, depending on your financial situation, it’s important to weigh up the pros and cons of buying, or opting for a leasing option. First of all, let’s look at why you might decide to buy the item… Buying: the pros and cons: - Pro: It’s a tangible asset – when you buy an item, you own the item outright and it will appear on your balance sheet as one your business assets. As such, by owning these assets outright you increase the perceived capital and value of your business. You can also claim the cost of the asset against your capital allowance for tax purposes. - Pro: It’s yours for the life of the asset – once you own the item, you have full use of the equipment for the duration of the life of the asset. Your use of the asset isn’t reliant on you being able to keep up regular lease payments, and if your financial circumstances change then you can sell the asset to free up the capital. - Con: It’s an expensive outlay – paying for the item up-front is a large outlay for the business and will require you having the cash to cover this cost. Spending a large lump sum in this way may take cash away from other areas of the business, so you need to be 100% sure that this purchase is the right decision and a sound investment. - Con: You may require extra funding – if you don’t have the liquid cash available to buy the item outright, you may need to take out a loan. Asset finance is available from funding providers, but does tie you into a loan agreement that will add to your liabilities as a business – reducing your worth on the balance sheet. Leasing: the pros and cons: - Pro: Leasing has a cheaper entry point – if the item you need to purchase has a large price tag, leasing allows you to make use of the asset without the cost of buying it in full. For start-ups and smaller businesses with minimal capital behind them, this can make leasing a very attractive option. You may not own the asset, but you can make use of it – and this may be the difference between the success or failure of your business. - Pro: You can spread the cost – there is still an associated cost of leasing, but you can spread the cost over a longer period, making it easier to find the necessary liquid cash to meet your lease payments. With this money saved, you can then invest in other areas of the business, helping you to expand, grow and bring in more customers and revenue. - Con: You don’t own the asset – there are different types of leasing agreement. Under a capital lease, you do own the asset (once you’ve paid if off). But if you opt for an operating lease, this is a more short-term lease and you won’t own the asset at the end of the contract. Ownership does have its advantages (including being able to sell off the asset if required) so it’s important to consider what kind of leasing agreement you’re entering into and what the advantages/disadvantages may be. - Con: You may pay more in the long run – most leasing agreements will attract additional costs and interest on your agreement, so you may well end up paying more than the market price for your asset in the long term. If you can cope with the higher cost, this is fine, but bear in mind that buying outright may have offered greater value. - Con: You may lose the use of the asset – if you can’t keep up your lease payments (due to poor cashflow for example) then the owner of the lease agreement may recall the asset. If this item is crucial to your business model, losing this key asset can have a profound impact on your ability to operate. In this respect, leasing is a more risky prospect, but also an easier option for businesses with less cash to splash.Talk to us about whether buying or leasing is the best way forward. Whether you opt to buy or lease your equipment isn’t always a straightforward decision to make – so it’s a good idea to consult with your accountant early on in the decision-making process. We’ll help you review your current financial position, assess your available cashflow and look at your regular cost base to decide whether buying or leasing is the right thing for your business.
More Posts